

The muted oil price response to the recent Israel-Iran conflict suggests that the influence of Middle East politics on energy markets is waning, due to changes in global supply.
The muted volatility in oil prices during the Israel-Iran war has highlighted the growing efficiency of energy markets and the fundamental changes in global crude oil supply, suggesting that Middle East politics will no longer be the dominant force in oil markets as it once was.
The spike in oil prices following Israel’s surprise attack on Iran was significant but relatively modest given the high risks associated with conflict between rival Middle Eastern players.
Benchmark Brent crude, often seen as a measure of geopolitical risk, rose from below $70 a barrel on June 12, the day before Israel’s initial attack, to a peak of $81.40 on June 23 following US airstrikes on Iran’s nuclear facilities.
However, prices fell sharply the same day after it became clear that Iran’s retaliation against Washington—a pre-announced attack on a US military base in Qatar that caused limited damage—was essentially a de-escalation.
Prices then fell below pre-war levels, to $67 on Tuesday, after US President Donald Trump announced that Israel and Iran had agreed to a ceasefire.
The worst-case scenario for energy markets—Iran blocking the Strait of Hormuz, through which nearly 20% of the world’s oil and gas supplies pass—did not materialize. In fact, there has been virtually no disruption to flows from the Middle East during the conflict.
So, for now, it seems that markets were right not to panic.
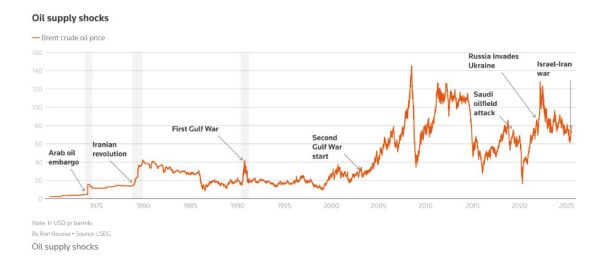
Risk premiums are shrinking
The low-to-high volatility of just 15% during the conflict suggests that oil traders and investors have sharply reduced their risk premiums for geopolitical tensions in the Middle East.
Consider the impact on prices of previous tensions in the region. The 1973 Arab oil embargo nearly quadrupled oil prices. The disruption of Iranian oil production after the 1979 revolution doubled spot prices.
Iraq’s invasion of neighboring Kuwait in August 1990 caused Brent crude to double to $40 a barrel by mid-October. And the start of the second Gulf War in 2003 led to a 46% spike in prices.
Although many of these supply disruptions – with the exception of the oil embargo – were ultimately short-lived, markets reacted violently.
Of course, one must be careful when comparing conflicts, as each has its own unique characteristics, but the oil market’s response to major disruptions in the Middle East has been – at least in percentage terms – declining in recent decades.
Rationality and Savviness
There are several potential explanations for this shift in perceptions of the value of the Middle East risk premium.
First, markets may simply be more rational than they used to be, thanks to access to better news, data, and technology.
Investors have become extremely adept at monitoring energy market conditions in near real time. Using satellite ship tracking and aerial imagery of oil fields, ports, and refineries, traders can monitor oil and gas production and shipments, giving them a better understanding of the supply-demand balance than they have in decades.
In this latest conflict, markets have certainly responded rationally. The risk of supply disruption has increased, so prices have increased, but not excessively, as there are significant doubts about Iran’s ability or willingness to disrupt shipping for an extended period.
Another explanation for the limited price volatility could be that regional producers – also acting rationally – have learned from previous conflicts and have responded accordingly by building alternative export routes and storage to limit the impact of any disruptions in the Gulf.
Saudi Arabia, the world’s top oil exporter, producing about nine million barrels per day, nearly a tenth of global demand, currently has a crude pipeline running from the Gulf coast to the Red Sea port city of Yanbu to the west, which would allow it to bypass the Strait of Hormuz. The pipeline has a capacity of five million barrels per day and could be expanded by another two million barrels per day.
In addition, the United Arab Emirates, another major OPEC and regional producer, with an output of about 3.3 million barrels per day, has a 1.5 million barrel per day pipeline connecting its onshore oil fields to the Fujairah oil port east of the Strait of Hormuz.
Both countries, as well as Kuwait and Iran, also have large storage facilities in Asia and Europe, allowing them to continue supplying customers even during short disruptions.
Changing Fundamentals
Perhaps the most important reason for the world’s waning concerns about disruptions in Middle Eastern oil supplies is the simple fact that a smaller proportion of the world’s energy supply now comes from the Middle East.
In recent decades, oil production has skyrocketed in new basins such as the United States, Brazil, Guyana, Canada and even China.
According to the International Energy Agency, OPEC’s share of global oil supply has fallen from more than 50% in the 1970s to 37% in 2010 and further to 33% by 2023, largely due to the shale oil boom in the United States, the world’s largest energy consumer.
To be sure, the global oil market was already quite well supplied before the latest conflict, which further reduces concerns.
Ultimately, then, the Israel-Iran war is further evidence that the link between Middle East politics and energy prices has loosened, perhaps permanently. So geopolitical risks may continue to rise, but don’t expect energy prices to follow suit.
Reuters
>> Other news:
>> 4 main types of services of Advantage Logistics:
>> Our contact:
-
-
- Address: 3rd Fl., 55 Nguyen Van Giai Str., Dist 1, HCMC, Vietnam.
- Email: nicky@advantage.vn / truc@advantage.vn
- Hotline (cell/ zalo/ viber): 0909.054.866 (Mr.Quyền) / 0938.444.043 (Mr.Trực)
- Web: https://advantage.vn
-


